Liquidity now. Upside later.
KONE acquires control while the founder remains involved. Economics can combine fixed consideration with retained equity or performance-linked upside, so the founder participates in value created after the transaction.
Whether you want liquidity and a second growth chapter or a clean path to retirement, KONE starts with your goals, your clients, your team and the economics of the business.
These are guidelines rather than hard rules. The quality of the business, the client base and the fit with the owner matter more than a perfect spreadsheet range.
The right structure depends on what you want after closing.
KONE acquires control while the founder remains involved. Economics can combine fixed consideration with retained equity or performance-linked upside, so the founder participates in value created after the transaction.
For founders planning retirement, recovering from burnout or moving to a new chapter, KONE can evaluate a traditional 100% sale with an agreed transition period — for example, several months of handover before the founder steps away.
A valuation multiple is an output. We first understand what sits underneath the earnings and what must survive the transition.
Recurring revenue, pricing, service mix, customer concentration and durability.
Retention, client profile, geography, referral sources and churn.
Operating earnings after normalizing owner compensation and one-time items.
Leadership depth, employee stability and the work that currently depends on the founder.
Accounting workflows, tax processes, software, data access, licensing and controls.
Pricing, marketing, cross-sell, capacity, local density and operating improvement.
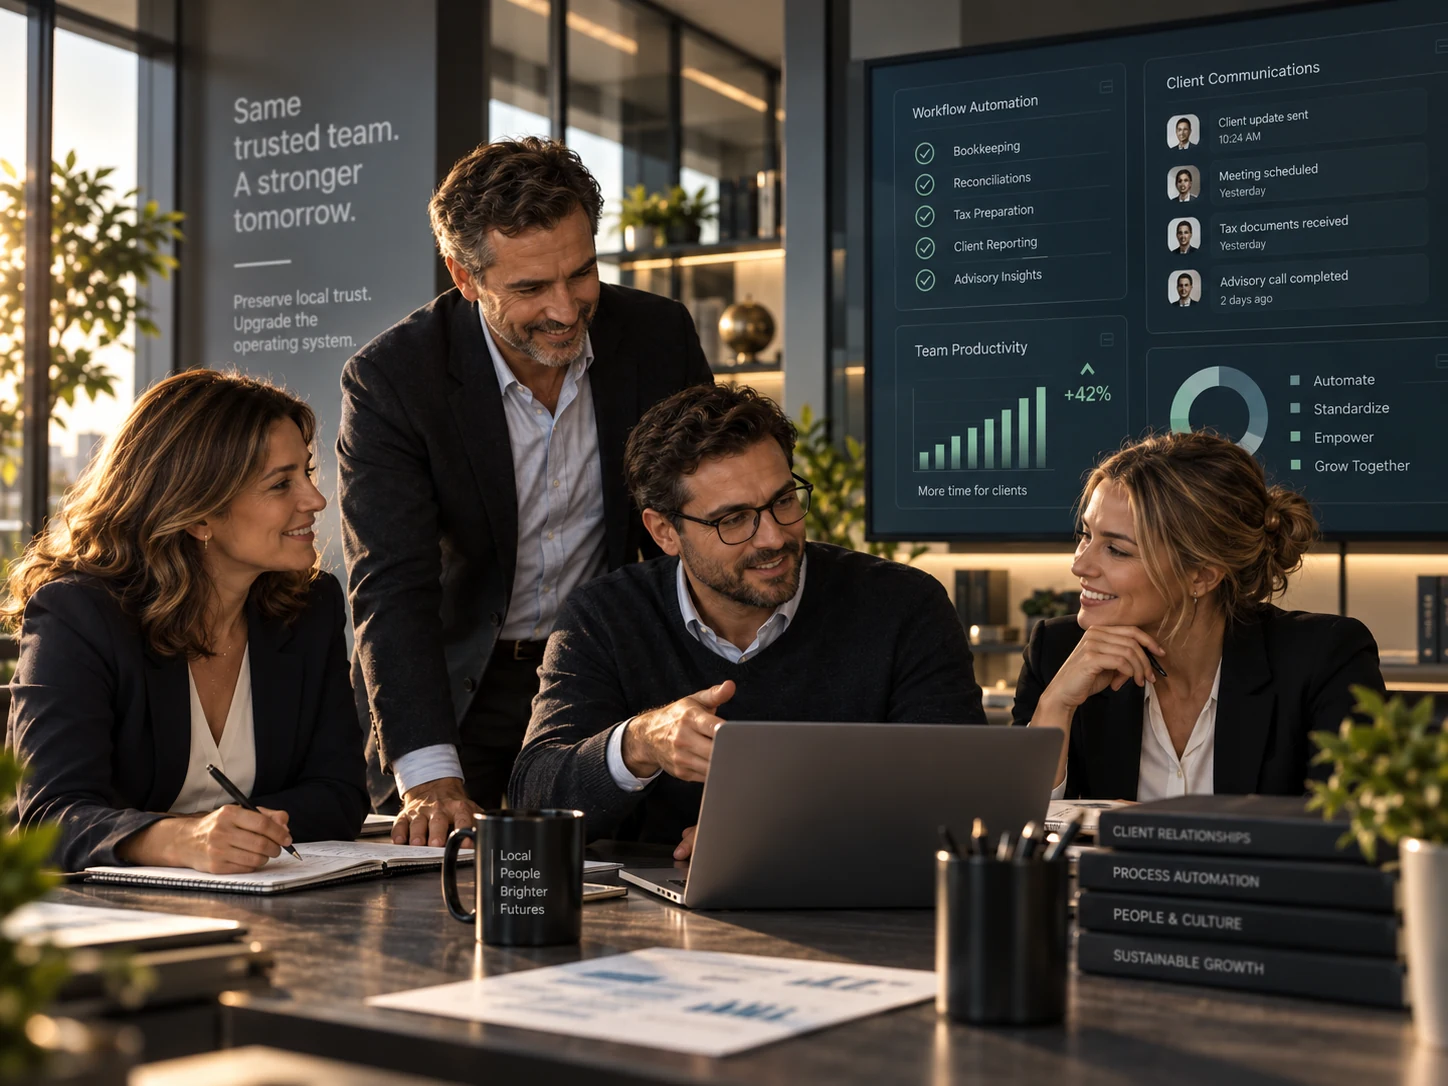
KONE standardizes workflows, management reporting, client communication and growth systems while keeping qualified professionals accountable for the work. The goal is a stronger business that does not rely on one person for every decision.
See the operating system →Because accounting teams regularly see client P&Ls, cash flow and operating patterns, they are often the first to notice when a client may need help beyond accounting. With client permission and clear compliance rules, KONE can turn those signals into useful introductions to vetted providers — creating commission revenue for the firm and an incentive layer for the accountant who surfaces the opportunity.
A first note can be as simple as annual revenue, approximate SDE/EBITDA, client count, service mix and whether you want to stay involved or transition out.
No. KONE can evaluate a founder-partnership structure where KONE acquires control and the owner retains economic upside, or a full-sale structure when the owner wants complete liquidity and a defined transition out.
Yes. For owners who want to retire, are burned out or want a new direction, KONE can evaluate a traditional full-sale transaction with an agreed handover period, often structured around the needs of the business and client relationships.
Continuity is evaluated deliberately. Strong teams, reputation, service quality and client relationships are core assets that KONE aims to preserve while improving the operating system around them.
Recurring clients, annual revenue, normalized owner earnings or EBITDA, geography, service mix, client concentration, team size, growth history and your preferred transition path are usually enough to begin.